Emergency line answered 24/7

Serving Miami-Dade, Broward & Palm Beach counties

info@restorationusa.com
Call (954) 289-0566 Request service

Emergency line answered 24/7

Insurance claims

Water damage insurance claims in Florida, explained plainly

You own your claim. Here's how the process usually works, what policies tend to cover, and the documentation that helps an adjuster make a decision.

First 24 hours

What to do right after the damage

  1. 1

    Stop the source and stay safe

    Shut off the water and cut power to wet rooms. Your policy expects you to take reasonable steps to prevent further damage.

  2. 2

    Photograph everything first

    Wide shots of each room, close-ups of damage, the source, and damaged belongings. Before anything is moved or thrown out.

  3. 3

    Report the claim promptly

    Call your insurer or agent and get a claim number. Florida generally requires notice of a new property claim within one year of the date of loss, but sooner is always better.

  4. 4

    Start mitigation

    Extraction and drying are mitigation, the work that keeps the loss from growing. It does not need to wait for the adjuster.

  5. 5

    Keep receipts and a list

    Hotel stays, meals, equipment rental, and damaged items. Keep everything that was removed until the adjuster says otherwise, or photograph it thoroughly.

Insurance companies

Insurance companies we've worked with

We have handled water, mold, storm, and fire claims for policyholders of these carriers, so we know what their adjusters ask for. Don't see yours? We work with your insurer either way.

  • Citizens Property Insurance
  • Universal Property & Casualty
  • Tower Hill Insurance
  • State Farm
  • Allstate
  • USAA
  • Progressive
  • ASI
  • American Modern
  • Liberty Mutual
  • Nationwide
  • Farmers Insurance
  • AAA
  • Amica
  • The Hanover
  • Horace Mann

Names are listed to show experience only. Restoration USA is not affiliated with or endorsed by these companies. We work for you, the property owner, and your insurer makes all coverage decisions.

Coverage

Which policy covers what

Homeowners (HO-3)

Usually covers

Usually covers sudden and accidental water damage, such as a burst supply line or an appliance overflow.

Watch for

Gradual leaks, wear and tear, and rising floodwater are typically excluded. Some policies cap or exclude mold.

Condo unit owners (HO-6)

Usually covers

Covers what the unit owner is responsible for under the association's documents, typically interior finishes, cabinets, appliances, and contents.

Watch for

Under Florida's condo statute, the association's master policy generally covers the building itself. Which policy pays depends on where the leak started and the declaration.

Flood (NFIP or private)

Usually covers

Covers damage from rising water: storm surge, overflowing canals, and street flooding.

Watch for

Homeowners policies almost never cover flood. NFIP policies generally have a 30-day waiting period after purchase, so buy before you need it.

Commercial property

Usually covers

Covers the building and business property under the terms of the policy; some include business interruption.

Watch for

Documentation of downtime and the timeline of work matters for business interruption claims.
Documentation

What we document for your adjuster

Adjusters approve what they can verify. Our job records make the loss easy to verify: where the water came from, what it reached, how wet each material was, and how it was dried.

  • Dated photos of the source, each affected room, and removed materials
  • Moisture maps and daily readings for every affected material
  • Equipment logs: what was placed, where, and for how long
  • Water category and the reason any material was removed
  • An itemized scope of work for mitigation and repairs

We are a restoration contractor, not a public adjuster. We don't interpret your policy or negotiate your settlement. We make sure the facts are clear.

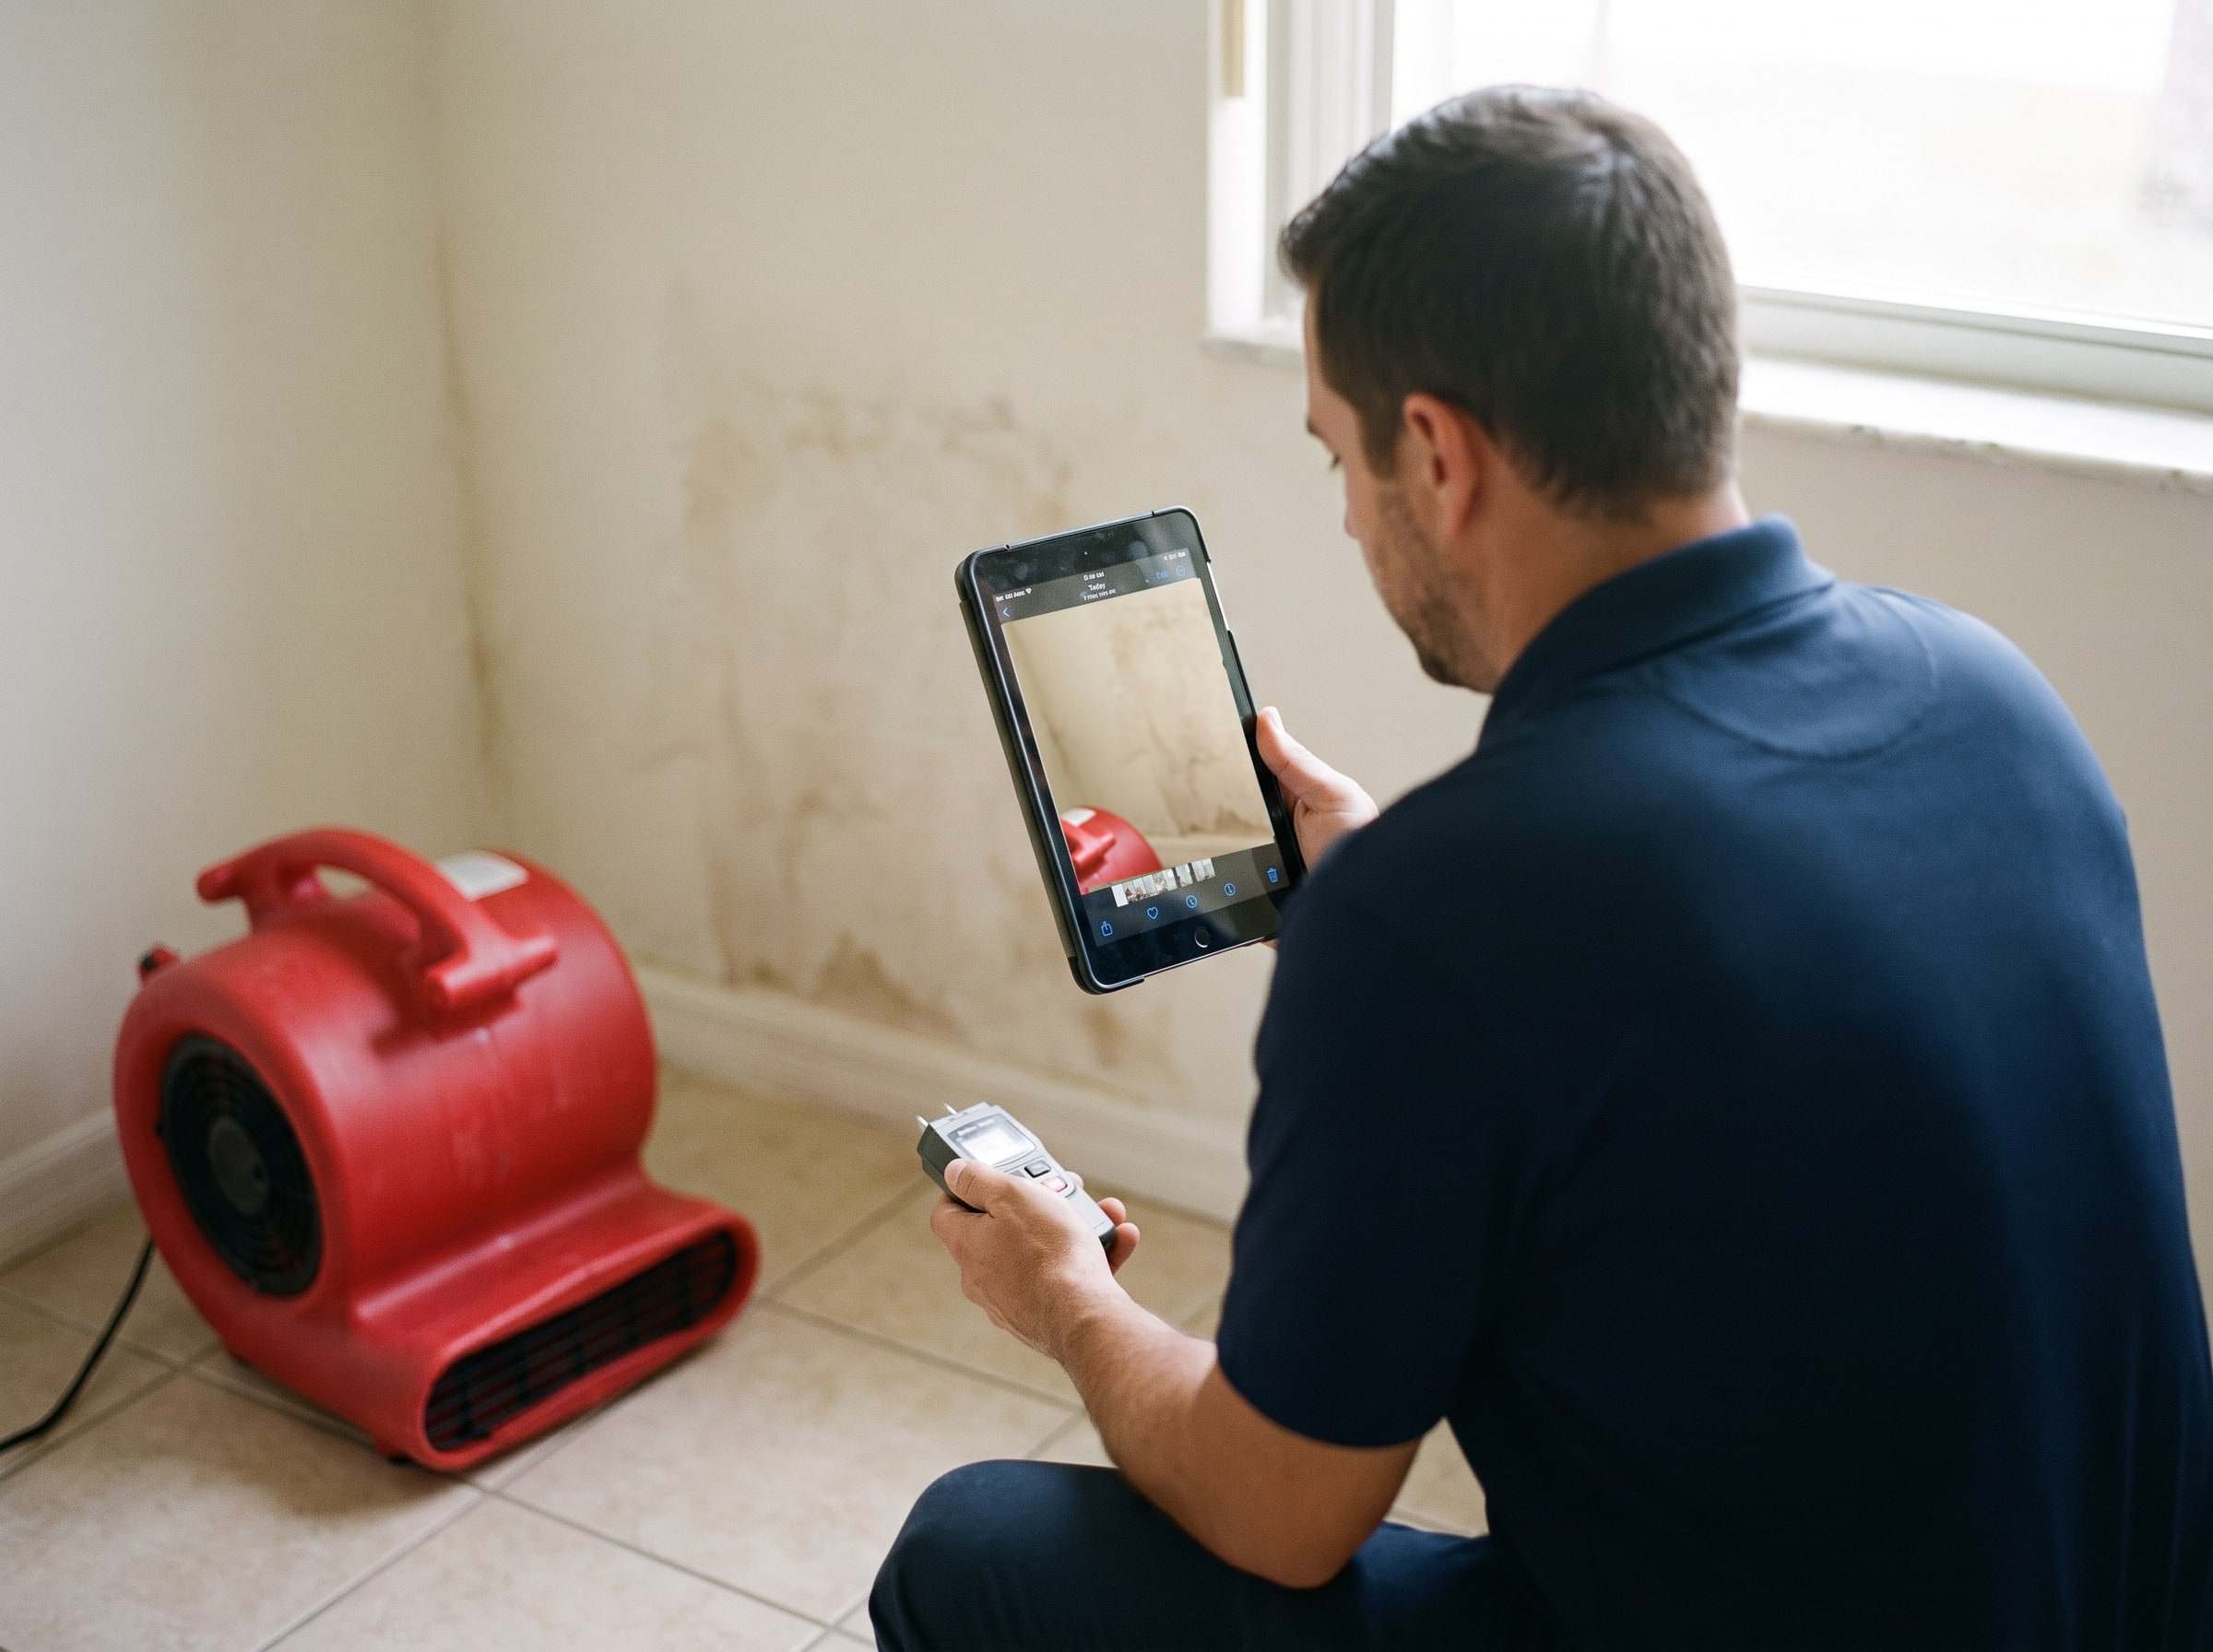
Technician photographing a water-stained wall with a tablet and holding a moisture meter to document the loss for insurance

How a job runs

Respond. Recover. Restore.

  1. 01

    Respond

    Stop the damage from spreading.

    1. Step 1: You call, we dispatch

      We answer 24/7. We walk you through shutting off the water and power to wet areas, then schedule a crew.

    2. Step 2: Inspect and map moisture

      Meters and thermal imaging show where the water went, including inside walls and under flooring. Starting conditions are photographed.

  2. 02

    Recover

    Get the water out and the structure dry.

    1. Step 3: Extract standing water

      Extraction removes the bulk of the water fast, which shortens drying time more than anything else.

    2. Step 4: Dry and monitor daily

      Air movers and dehumidifiers are set for the space. We take readings every day and adjust until materials reach the dry standard.

  3. 03

    Restore

    Return the property to pre-loss condition.

    1. Step 5: Clean, sanitize, repair

      Affected areas are cleaned and treated. Materials that could not be saved are replaced.

    2. Step 6: Close out the documentation

      You get the photos, moisture logs, and itemized scope your adjuster needs, so the claim is supported by records.

FAQ

Insurance questions

Do I have to wait for the adjuster before drying starts?

No. Mitigation, meaning extraction and drying, is how you prevent further damage, which your policy expects. We document the conditions before and during the work so the adjuster can see what we found even if they inspect after drying has started.

Can I choose my own restoration company?

Generally, yes. Some Florida policies include optional managed repair programs with their own rules, so read your policy or ask your agent. For emergency mitigation, you can call us right away either way.

Will you bill my insurance company?

Yes. For covered claims, we bill your insurance company directly. You pay your deductible and anything your policy does not cover. We provide the itemized scope, photos, and moisture documentation the adjuster uses to evaluate the claim, and we explain the paperwork before work starts so there are no surprises.

What is assignment of benefits, and do you require it?

Assignment of benefits (AOB) transferred a policyholder's claim rights to a contractor. Florida no longer allows AOB agreements for property policies issued on or after January 1, 2023. You stay in control of your claim.

What is a hurricane deductible?

Florida policies usually have a separate hurricane deductible, commonly 2, 5, or 10 percent of the dwelling coverage, that applies to losses from a named hurricane. It is often much higher than the regular deductible. Your declarations page lists it.

Do you negotiate my settlement?

No. We are a restoration contractor, not a public adjuster or an attorney. We document the damage and the work; the coverage decision and the settlement are between you and your insurer.

Don't wait. Go with the pros.

Water in the building right now?

Call the 24/7 line. We will help you stop the source, tell you what to move, and get a crew scheduled. Not urgent? Send a request and we will call you back.

Call 24/7 (954) 289-0566
  1. 1 We answer 24/7, day or night
  2. 2 We help you stop the water and protect belongings
  3. 3 We schedule a crew and tell you when to expect them

On call 24/7

Free inspection

Schedule a no-cost on-site inspection. A restoration specialist will contact you within a few minutes to confirm the details.

Enter your name.

Enter a 10-digit phone number.

Enter a 5-digit ZIP code.

Choose the type of damage.

Active water leak or suspect you have mold? Call (954) 289-0566 to speak with a restoration specialist right away. Our specialists are standing by and on call 24/7.

Recognized by

  • Angi Super Service Award 2025
  • Thumbtack Top Pro 2026
  • Expertise.com Best Water Damage Restoration Services in Pompano Beach 2026
  • 30+ YEARS OF INDUSTRY EXPERIENCE
  • BBB Accredited Business, A+ rating
  • IICRC Certified Firm
Call 24/7 (954) 289-0566 Request service